Does Home Insurance Cover Wood Rot in BC?
By STOP THE ROT CO.
Short answer: usually not, and it’s worth understanding why before you’re standing in a crawl space wondering whether to file a claim. This is general information about how standard homeowner policies in BC typically treat wood rot, not insurance advice, your own policy wording controls, and an adjuster or broker is the one who can tell you exactly where you stand.
Why Most Policies Exclude It
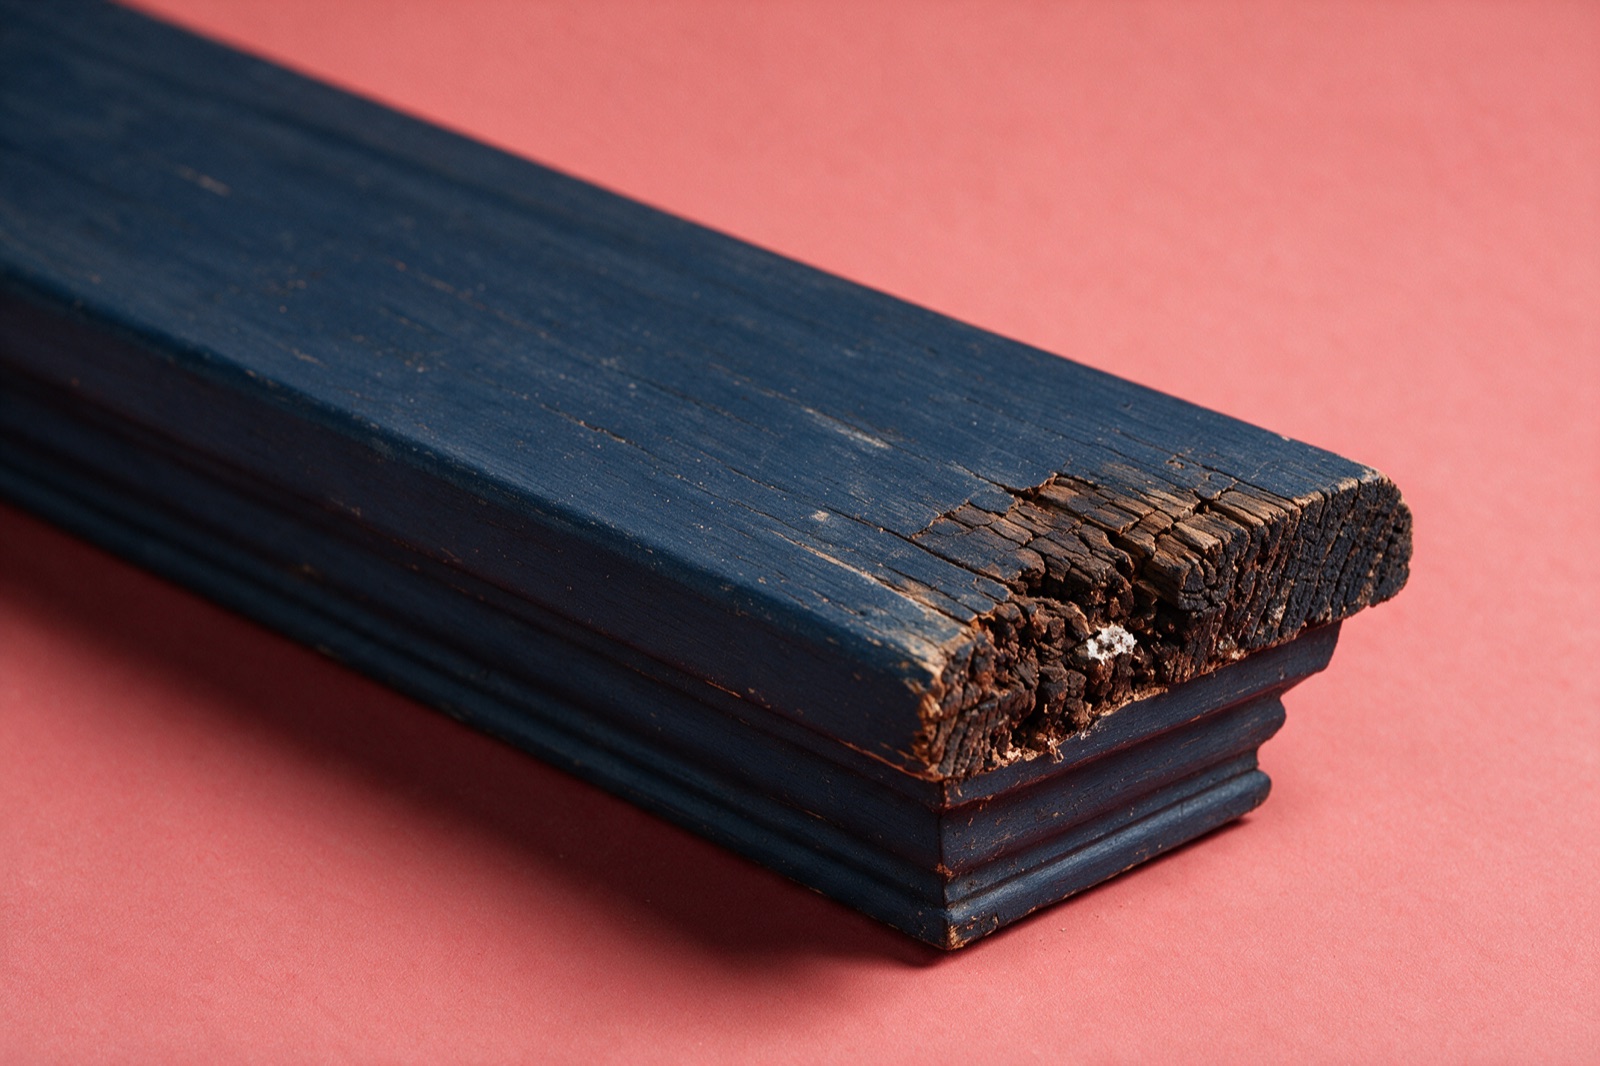
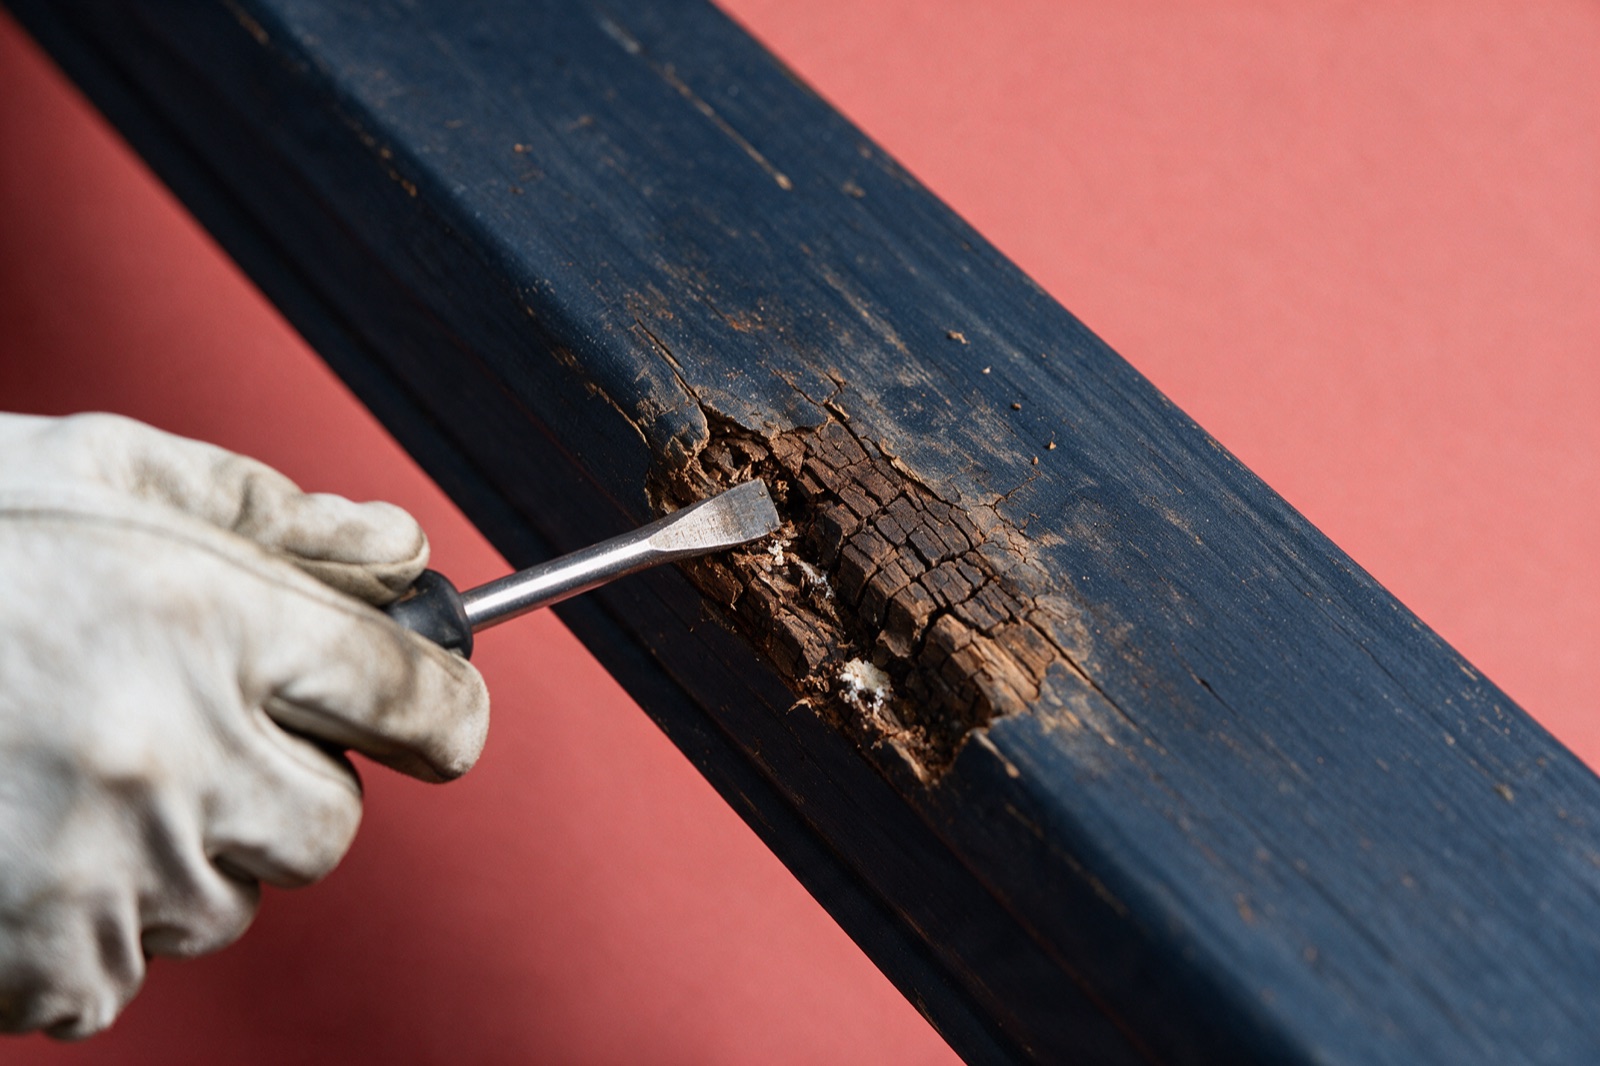
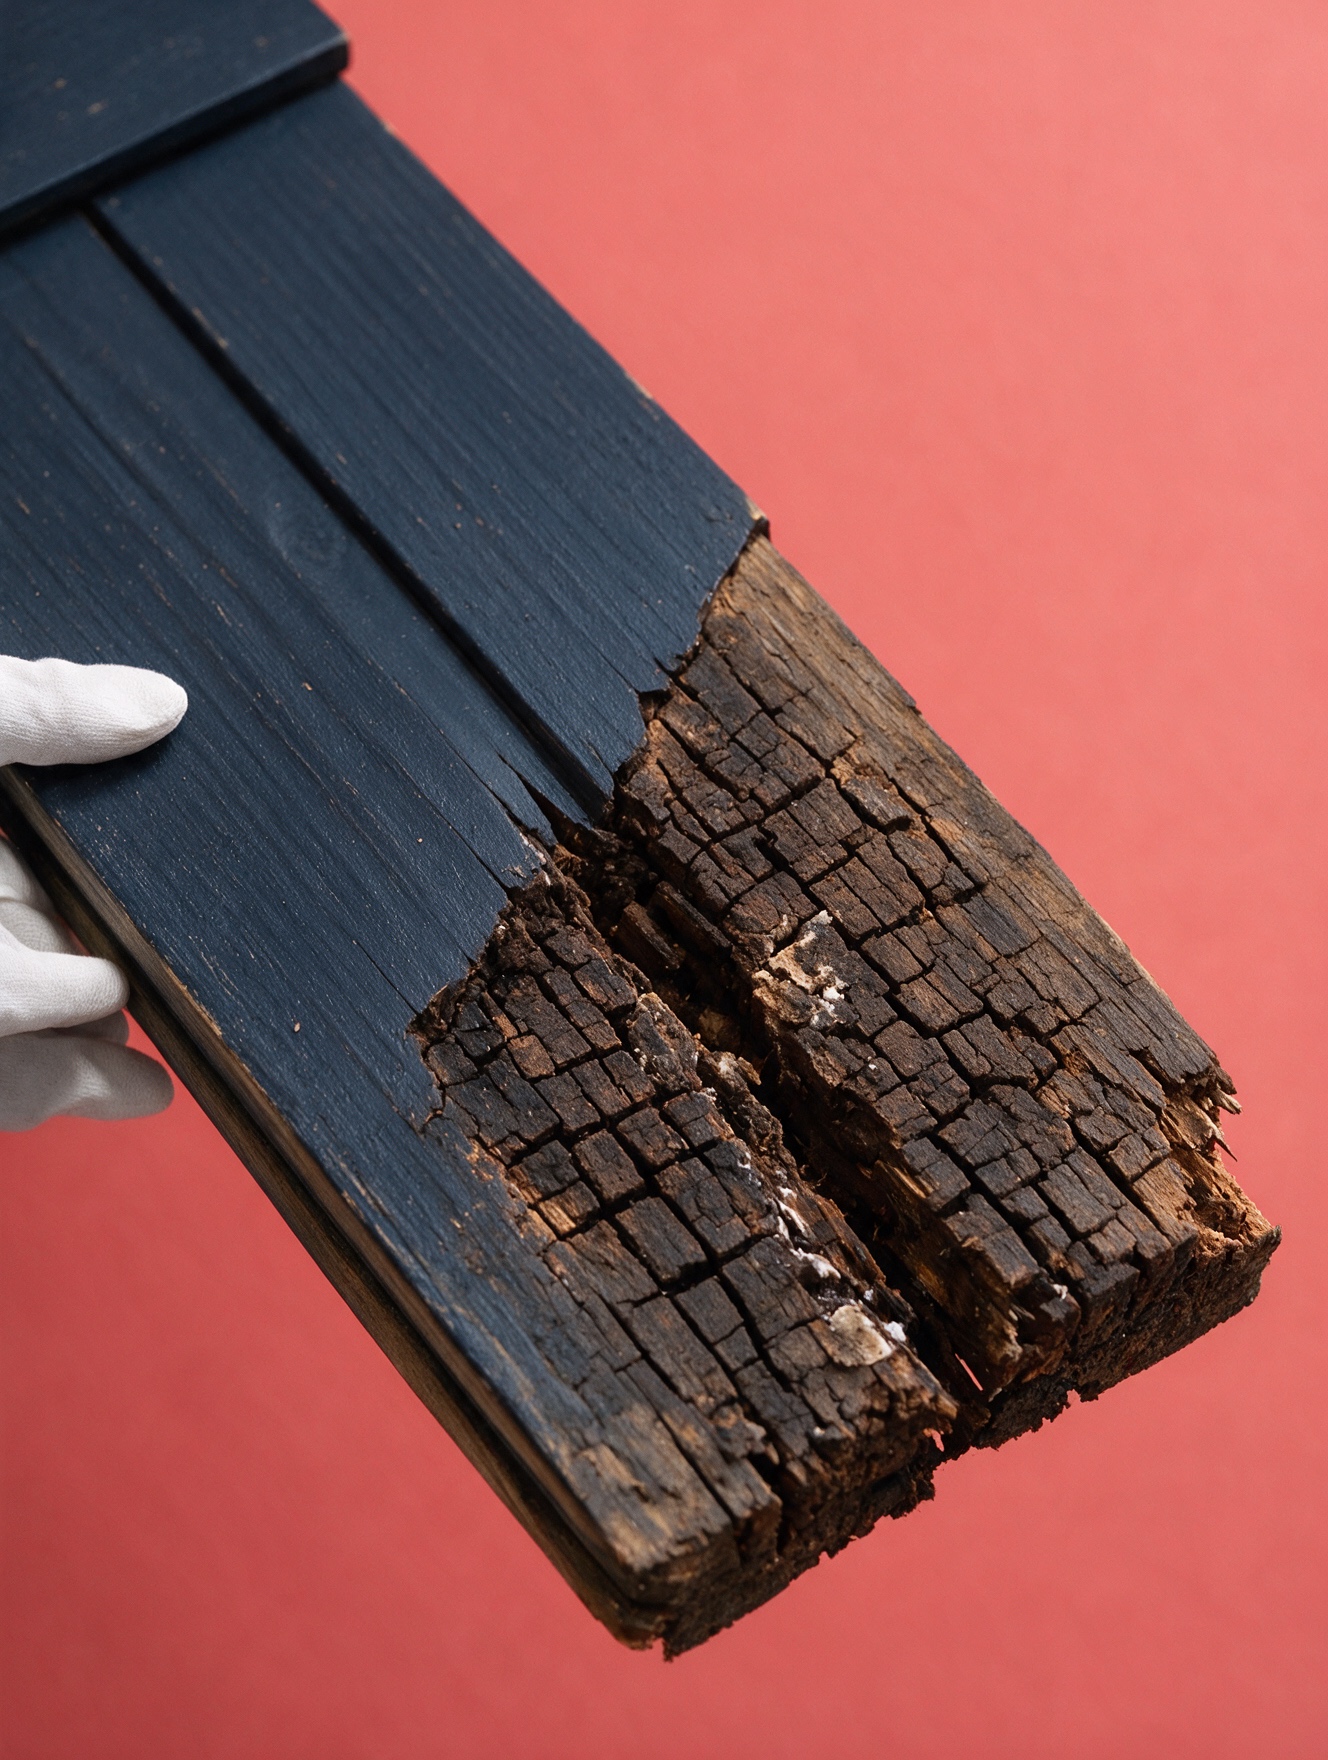
Standard homeowner insurance in Canada is built to cover sudden, accidental loss, a burst pipe, a wind-damaged roof, a kitchen fire. Wood rot almost never qualifies, because it’s the product of gradual moisture exposure over months or years, not a single, identifiable event. Most policies explicitly exclude damage caused by “wear and tear,” “deterioration,” “faulty workmanship,” or “inherent vice,” and wood rot sits squarely in that category from an insurer’s perspective, however sudden the discovery feels to the homeowner.
The One Distinction That Matters
There’s a real difference between the rot and its cause. If a pipe bursts and floods a wall cavity, the sudden water damage itself is typically covered. But if that same wall cavity has been slowly rotting for two years because of an undetected slow leak, that’s treated as gradual deterioration, and gradual deterioration is exactly what standard policies are written to exclude. The claim doesn’t hinge on whether wood rot is present, it hinges on whether the water that caused it arrived suddenly or slowly, and that distinction is usually where a claim gets approved or denied.
What Can Push a Claim the Other Way
A few circumstances make coverage more plausible, though never guaranteed:
- A clearly sudden event. A burst pipe, a failed appliance hose, or storm-driven water intrusion that caused damage in a short, identifiable window.
- Resulting damage from a covered peril. Some policies cover the rot that results directly from an otherwise-covered sudden loss, even if the rot itself took a few weeks to set in after the event.
- Endorsements or riders. Some insurers offer optional water-damage or “hidden water” endorsements that extend coverage further than a standard policy. Worth asking a broker about directly if a home has a known moisture-prone spot.
Documentation Is What Actually Decides a Borderline Claim
Insurers don’t take a homeowner’s word for when damage started, they look for evidence. A documented moisture-meter reading, dated photos, and a written assessment from whoever diagnosed the rot are what separate a claim that gets a fair look from one that gets an automatic denial. This is exactly why we document every inspection with a real moisture reading rather than a visual guess, it’s the same record that matters if a claim ever gets filed, not just the repair itself.
The Practical Takeaway
Don’t wait on an insurance answer before addressing wood rot. Coverage is the exception, not the rule, and the underlying damage only gets more expensive the longer it sits. Get a documented inspection first, that record is useful whether or not a claim ever gets filed, then talk to your broker with real facts in hand instead of a guess.
Not sure whether what you’re seeing is worth a claim conversation?
A documented inspection is the record that matters most here, see How We Fix It for how we diagnose and document every job.
Sources: Insurance Bureau of Canada, homeowner policy guidance on gradual damage and maintenance exclusions; standard BC homeowner policy wording on wear, tear, and deterioration exclusions.